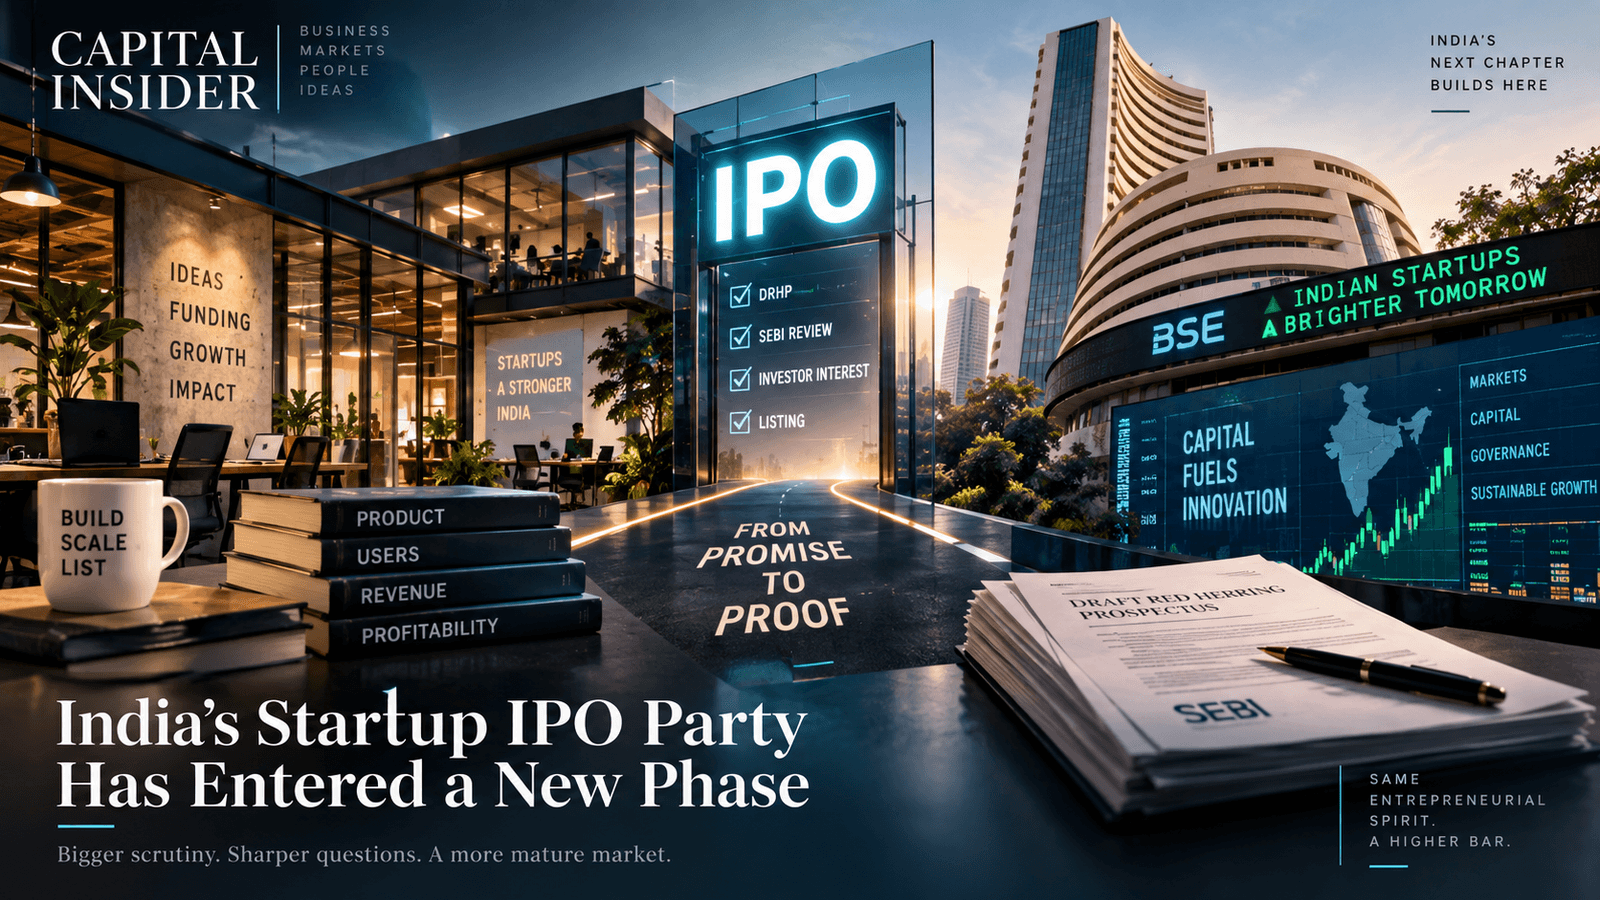
India’s startup IPO pipeline remains active, but public markets are putting greater focus on valuation, profitability, cash flow and capital efficiency.
India’s startup IPO market is still moving. But the conversation around what makes a company ready for the public markets is changing.
At least 47 startups are being tracked for potential listings in 2026, with 23 having filed DRHPs and another 24 preparing plans, according to StartupFeed’s IPO tracker. The companies in the pipeline include large names such as Flipkart, Zepto and OYO, with the group targeting more than ₹47,000 crore in potential fundraising. In 2025, 18 technology companies raised ₹41,248 crore through IPOs, according to industry data cited in the same tracker.
The important shift is not simply the number of companies coming to market. It is what investors can ask of them once they get there.
Manjushri Sharma, a SEBI-registered Research Analyst, describes the current environment as “liquidity-supported, but fundamentally filtered.” She argues that investors are increasingly looking beyond revenue growth and market opportunity towards sustainable unit economics, cash generation, operating leverage and valuation against listed peers.
That distinction matters because a private funding round and a public listing operate under very different conditions. A startup can build a valuation around future potential when only a relatively small group of investors is setting the price. Once listed, the company is continuously compared with businesses whose financial performance and market value are visible to everyone.
For India’s next generation of startup IPOs, that transition is becoming the real test.
Zepto Faces the Public-Market Valuation Test
Zepto is one of the clearest examples.
The quick-commerce company has grown at extraordinary speed. Its revenue rose from about ₹4,544 crore in FY24 to roughly ₹23,128 crore in FY26, while it processed around 640 million orders during FY26. The other side of that growth has been its loss profile. Its net loss widened from around ₹1,215 crore in FY24 to roughly ₹5,905 crore in FY26.
The numbers have made unit economics an important part of the valuation conversation.
An analysis cited by INDmoney put FY26 losses at roughly ₹3 per order for Blinkit, ₹79 for Zepto and ₹85 for Swiggy Instamart. The comparison does not by itself establish why investors value each business differently, but it illustrates the question public-market investors can ask: how much economic value is being created from each additional unit of growth?
That question becomes particularly relevant when a company’s private valuation is used as a reference point.
Zepto paused its IPO process while pursuing a reported $4.5 billion pre-IPO valuation, below the $7 billion valuation attached to its previous funding round. Its Updated Draft Red Herring Prospectus remains on record with SEBI, proposing an ₹8,010 crore fresh issue and an Offer for Sale of up to 11.34 crore shares.
The company is also reported to be raising around ₹1,000 crore in a pre-IPO bridge round, with the funding linked to increasing its domestic shareholding. Separately, Zepto’s advertising business has expanded sharply, with advertising revenue reported at ₹1,636 crore in FY26 compared with ₹49 crore in FY24.
Sharma’s framework is useful here. She argues that a previous private funding valuation should not automatically become the benchmark for an IPO. Public investors can instead compare the company with listed peers and ask what future earnings and cash flows justify the price.
In other words, the question is no longer simply how quickly Zepto can grow. It is how efficiently that growth can translate into economic value.
Moneyview Shows How IPO Structures Can Change
Moneyview offers a different example because its IPO is moving ahead.
Whizdm Innovations, the parent company of Moneyview, is scheduled to open its public issue on September 24, with the issue closing on September 28 and trading expected to begin on October 1. The company is seeking a valuation of up to about ₹5,985 crore, according to Reuters.
Its operating numbers are also growing. Consolidated revenue increased 43.3% year-on-year to ₹3,351 crore in FY26, while profit before exceptional items rose 65.4% to ₹397 crore.
Yet the structure of the proposed IPO has changed from the company’s earlier filing.
Moneyview reduced its fresh issue from ₹1,500 crore to ₹750 crore, a 50% cut. The Offer for Sale was also reduced, from 136.1 million shares to 100.49 million shares. Promoters Puneet Agarwal and Sanjay Aggarwal are among those selling shares, alongside early investors including Accel, Tiger Global and Ribbit Capital.
Reuters reported that the company did not specify why the offer size was reduced.
That makes the change interesting, but it does not establish that investors rejected the original structure. The safer conclusion is that IPO structures can evolve between an initial filing and the final offer as companies prepare for public markets.
Moneyview also illustrates another point raised by Sharma: profitability cannot be viewed as a simple profitable-versus-loss-making test. Investors can tolerate investment-led losses when there is evidence of improving margins, operating leverage, declining cash burn and a credible path towards future cash generation.
CarDekho and PharmEasy Are Changing What Comes Before the IPO
The preparation for a public listing is also playing out on company balance sheets.
CarDekho, operated by Girnar Software, has been reported to be preparing a confidential IPO filing targeting an issue of around ₹3,000 crore at a valuation near ₹13,000 crore. The proposed structure is heavily weighted towards an Offer for Sale, with roughly ₹2,700 crore expected from selling shareholders and about ₹300 crore as fresh capital.
That matters because an OFS-heavy IPO serves a different purpose from a large primary fundraising. Much of the money goes to existing shareholders rather than the company itself.
CarDekho reported ₹1,177 crore in net cash and a standalone profit of ₹27 crore on ₹1,001 crore of revenue in FY25. The company has also restructured its insurance interests, including the combination involving InsuranceDekho and RenewBuy under Artivatic Data Labs.
PharmEasy parent API Holdings has taken a different route. In August, the company said it had become debt-free after repaying ₹1,050 crore of outstanding debt. It monetised a 9.9% stake in Thyrocare Technologies and used the proceeds alongside internal accruals to reduce its obligations. API Holdings retained a 51.02% controlling stake in the diagnostics company.
Across the wider startup IPO market, OFS has also become an important part of the capital raised. Industry data for 2025 puts OFS at roughly 52% of the ₹41,248 crore raised across 18 startup IPOs.
For venture investors from earlier funding cycles, public markets can provide a route to liquidity. For the companies themselves, however, the distinction between fresh capital and shareholder exits is increasingly relevant to investors assessing an IPO.
Confidential Filings Give Startups More Room Before Going Public
Another change is happening before investors even see the full prospectus.
According to market participants cited by Moneycontrol, 39 companies used SEBI’s confidential filing route between June 2025 and May 2026, compared with six in the previous 12-month period.
The mechanism allows companies to submit draft offer documents to SEBI and stock exchanges without immediately making the full prospectus public. Issuers can receive regulatory feedback, make changes and manage the timing of a wider public disclosure. The framework also provides an 18-month observation validity period compared with 12 months for a standard filing.
For companies still assessing market conditions, that flexibility can matter.

Gaurav Sood, Managing Director and Head of Equity Capital Markets at Avendus Capital, has described confidential filings as increasingly attractive when IPO timing is challenging. Trilegal partner Richa Choudhary has highlighted the ability to undergo regulatory review without immediate public disclosure, while IIFL Capital’s Prakash Bulusu has pointed to the flexibility to assess investor appetite and valuation expectations.
The growing use of the route does not mean companies are abandoning IPO plans. In many cases, it gives them more flexibility over when and how they approach the market.
Domestic Capital Is Keeping the IPO Window Open
There is also a counterweight to the greater scrutiny.
India’s domestic investor base has become substantially deeper, with demat accounts crossing 20 crore in 2025. Domestic mutual funds have also accounted for more than half of anchor allocations in several major offerings, according to industry data cited in the source material.
Narinder Wadhwa, Managing Director and CEO of SKI Capital Services, says domestic liquidity has become a structural stabiliser for Indian markets. Mutual funds, SIPs, insurance companies and other institutional channels are providing capital month after month, helping the market absorb periods of foreign selling.
But Wadhwa does not see domestic money as a complete substitute for foreign capital. In his view, domestic flows can provide stability while foreign flows can add momentum, particularly in large-cap stocks.
That distinction matters for startup IPOs. There is still capital available for new listings. The bigger question is whether a company’s growth story can stand up to continuous public-market scrutiny once the valuation is visible every trading day.
From Private-Market Promise to Public-Market Proof
India’s startup IPO pipeline has not disappeared. If anything, the number of companies preparing to test public markets shows that the opportunity remains significant.
What is changing is the test.
The private-market valuation that once served as the central reference point is no longer enough on its own. Revenue growth still matters, but investors can increasingly ask what sits underneath it: contribution margins, customer acquisition costs, cash burn, operating leverage, governance, capital allocation and the valuation being demanded.
Sharma’s central distinction captures the shift well: from private-market story to public-market evidence.
For India’s next wave of startup IPOs, scale may get a company to the market. What happens after that will depend on how convincingly that scale translates into sustainable economics.
Read More :In IPO activity, India maintains global lead amid market uncertainty
Methodology
This article draws on public filings and disclosures from SEBI and companies, reporting from Reuters, Moneycontrol and Business Standard, industry IPO trackers, and interviews with market experts. Company financials and IPO structures have been cross-checked against available filings where possible. Expert comments represent their own views and do not necessarily reflect Capital Insider’s position. Where IPO plans or valuations are based on media reports rather than public filings, they are identified as such.